You've found a home you love. The price looks right. You've even calculated what the mortgage payment might be.
But have you calculated the whole payment?
For homebuyers in Jackson County, Michigan, there's an important detail that can make a meaningful difference in monthly affordability: property taxes.
Two homes with the same purchase price can have different monthly payments. And in Michigan, the property taxes shown on a real estate listing may not be what the next homeowner pays.
Understanding those differences before you make an offer can help you shop with confidence.
Your Mortgage Payment Is More Than Principal and Interest
When you see an online mortgage calculator, the payment shown may include only principal and interest.
Your actual monthly housing payment may include several components:
- Principal: The portion of your payment that reduces your loan balance.
- Interest: The cost of borrowing money.
- Property taxes: Taxes assessed by the applicable local taxing authorities, often collected monthly through a mortgage escrow account.
- Homeowners insurance: Coverage for the home, also commonly included in escrow.
- Mortgage insurance: An additional cost that may apply depending on your loan program, down payment, and other factors.
Homeowners association dues, when applicable, should also be considered in your housing budget, even when they aren't included in your mortgage payment.
The important question isn't simply, "How much house can I qualify for?"
It's "What monthly payment will feel comfortable for my household?"
Two Jackson County Homes. Same Price. Different Payments.
Imagine you're comparing two homes in Jackson County.
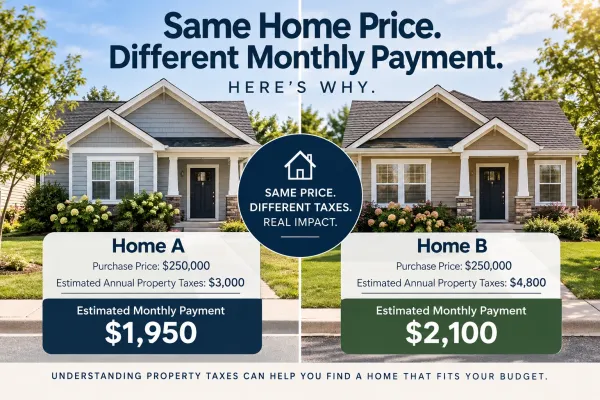
Both are priced at $250,000. You plan to use the same down payment, loan program, and interest rate for either home.
For illustration, let's assume their estimated annual property taxes are different:
| Comparison | Home A | Home B |
|---|---|---|
| Purchase Price | $250,000 | $250,000 |
| Estimated Annual Property Taxes | $3,000 | $4,800 |
| Monthly Property-Tax Amount | $250 | $400 |
That's a $150 difference every month—or $1,800 per year.
And that's before considering possible differences in homeowners insurance, HOA dues, or other housing expenses.
These figures are hypothetical examples, not actual tax estimates for particular Jackson County properties or townships.
The lesson is simple: Purchase price alone doesn't tell you what a home will cost each month.
Why Property Taxes Vary Across Jackson County
Jackson County includes communities such as Napoleon Township, Columbia Township, Grass Lake Township, Blackman Township, Spring Arbor Township, and the City of Jackson.
Each property belongs to a particular combination of local taxing jurisdictions, which may include a township or city, school district, county, and other authorities.
The tax rates—often called millage rates—can differ depending on those jurisdictions.
A property's taxable value, eligibility for exemptions, and any special assessments also affect its tax bill.
That means buyers shouldn't assume two similarly priced homes will have the same taxes, even when they're relatively close to one another.
A knowledgeable local Realtor can help you identify the relevant township, municipality, and school district for a property. Your mortgage professional can then help you understand how a reasonable tax estimate affects your projected monthly payment.
The Michigan Property-Tax Detail Every Buyer Should Understand
Here's something many Michigan homebuyers don't realize:
The seller's current property-tax bill may not be a reliable estimate of your future taxes.
Michigan generally limits annual increases in a property's taxable value while the same owner holds it, subject to the state's rules.
When a property changes ownership in a qualifying transfer, however, its taxable value generally becomes uncapped in the following calendar year.
That means someone who has owned a home for many years may be paying taxes based on a taxable value that's substantially below the property's current State Equalized Value (SEV).
After a qualifying sale, the next owner's taxable value may increase.
What does that mean for your mortgage payment?
Suppose a listing shows relatively low annual property taxes.
If those taxes reflect a longtime owner's capped taxable value, using that amount to estimate your future payment could understate your housing costs.
This doesn't mean taxes automatically jump to a specific percentage of the purchase price. A home's purchase price is not necessarily its SEV, and the actual taxable value is determined under Michigan law.
It means buyers should request an informed estimate rather than relying only on the current tax bill.
For more information, see the Michigan Department of Treasury's explanation of ownership changes and taxable-value uncapping.
Don't Forget Michigan's Principal Residence Exemption
If you're purchasing a home that will be your primary residence, you may qualify for Michigan's Principal Residence Exemption (PRE).
The PRE can exempt a qualifying principal residence from up to 18 mills of local school operating taxes.
That can make a difference when comparing estimated taxes for an owner-occupied home versus a second home or investment property.
Eligibility and filing requirements matter, so buyers should confirm their circumstances with the appropriate local assessor.
Learn more through the Michigan Department of Treasury's Principal Residence Exemption information.
How to Research Property Taxes Before Buying in Jackson County
Fortunately, buyers have several useful resources.
1. Michigan's Property Tax Estimator
The Michigan Property Tax Estimator allows you to select a county, municipality, and school district and estimate taxes using a property's SEV or taxable value, depending on whether you're estimating for a future or current owner.
As of October 2026, the estimator displays 2025 millage rates. It also has limitations regarding certain special assessments and jurisdiction-specific situations.
Use it as a planning tool—not a guarantee of your future tax bill.
2. Jackson County's Parcel Viewer
The Jackson County Parcel Viewer provides access to parcel and assessing information.
It can help you research a particular property and identify details to discuss with your Realtor or local assessor.
Remember that existing taxable-value information may reflect the current owner's circumstances rather than yours.
3. Your Local Assessor or Treasurer
For a property-specific question, the relevant township or city assessor and treasurer are valuable sources.
Ask about the property's SEV, taxable value, exemptions, special assessments, and what may change following a transfer of ownership.
4. Your Realtor and Mortgage Professional
Your Realtor can help you research the property and connect with local officials when questions arise.
Your mortgage professional can help translate estimated property taxes into the monthly payment figures you'll use when deciding what you can comfortably afford.
Both roles matter—and they work best together.
Property Taxes Aren't the Only Variable
Even after you've estimated property taxes, there are other pieces to consider.
Homeowners Insurance
Insurance costs can vary depending on the property, its characteristics, coverage choices, deductible, and insurer.
Getting a realistic insurance quote before closing helps avoid surprises.
Mortgage Insurance
Some mortgage programs require mortgage insurance, depending on the loan type and down payment.
That expense may affect your monthly payment and should be included in your comparison.
Loan Structure
Your down payment, interest rate, loan term, and mortgage program can all affect your payment.
Sometimes the best financing conversation isn't about chasing the lowest advertised interest rate. It's about evaluating the options available to you and choosing a payment structure that supports your broader financial goals.
Start With a Comfortable Payment, Not Just a Maximum Approval
A mortgage preapproval is an important part of preparing to buy a home.
But the maximum amount you're eligible to borrow isn't necessarily the amount you'll feel comfortable spending.
Think about your other financial priorities: savings, retirement contributions, transportation, home maintenance, travel, and the unexpected expenses that come with homeownership.
A home should fit your life—not require your entire life to revolve around the payment.
At @Home Mortgage, we believe buyers benefit from understanding their financing options and the full monthly housing cost before making major decisions.
That includes looking closely at estimated property taxes in the Jackson County communities where you're shopping.
Frequently Asked Questions
Will my property taxes go up when I buy a home in Michigan?
Not necessarily immediately, and not by a fixed amount. After a qualifying transfer of ownership, Michigan generally uncaps the property's taxable value in the following calendar year. The resulting tax bill depends on the property's value, applicable millage rates, exemptions, and other factors.
Can I use the taxes shown on a Jackson County real estate listing?
You can use them as a starting point, but they may reflect the seller's taxable value and exemptions. Ask for an estimate based on your anticipated ownership.
Do property taxes differ between Jackson County townships?
They can. The applicable local taxing jurisdictions, school district, millage rates, taxable value, and special assessments all matter. Compare specific properties rather than assuming a township-wide tax amount.
Are property taxes included in my mortgage payment?
Many mortgages use an escrow account to collect property taxes and homeowners insurance as part of the monthly payment. The arrangement depends on your loan terms and escrow requirements.
Who should I ask about property taxes before making an offer?
Start with your knowledgeable local Realtor and mortgage professional. For official property-specific information, contact the relevant local assessor or treasurer.
The Bottom Line
Two homes with the same asking price can have very different monthly housing costs.
For Jackson County homebuyers, understanding property taxes—and Michigan's rules about taxable value after a sale—is an important part of being prepared.
Before falling in love with a payment estimate from an online calculator, make sure you're looking at the complete picture.
Thinking about buying in Jackson County? Let's talk about what a comfortable monthly payment looks like for you.
@Home Mortgage is here to help you understand your financing options and make informed decisions throughout your homebuying journey.
Educational information only. Property-tax estimates, mortgage payments, and program eligibility depend on individual circumstances. Consult the appropriate local taxing authority for property-specific tax information.